Roughly one in five new U.S. business establishments does not make it through its first year, although survival varies by industry, location, and economic conditions, according to the U.S. Bureau of Labor Statistics. That makes the first 12 months less about chasing impressive numbers and more about proving that the business can attract customers, generate cash, and operate repeatedly.
Learning how to set business goals for the first year starts with one important shift: your goals should test your business assumptions, not merely describe your ambitions.
A goal such as “become successful” offers no direction. “Reach 40 recurring customers while maintaining positive monthly operating cash flow by December” gives you something you can actually manage.
Start With Evidence Before Choosing Numbers
New founders commonly begin with a revenue target. Revenue matters, but choosing $100,000 simply because it sounds ambitious is not planning.
Begin with four questions:
What are customers realistically willing to pay?
How many customers can you serve with your current capacity?
What does delivering each sale cost?
How much cash must remain available to keep operating?
The U.S. Small Business Administration recommends using market research to examine customer demand, market size, pricing, competition, and barriers to entry rather than relying only on assumptions.
The U.S. Census Bureau’s Business Formation Statistics also show how active the entrepreneurial market remains. It recorded 531,728 seasonally adjusted business applications in August 2026 alone. A large pool of new businesses means founders are competing not only with established companies but with other new entrants.
Before committing to aggressive growth goals, make sure you know which customer problem you are solving and why someone should choose you.
A short one-page business plan can help turn those assumptions into something measurable.
Set Only Three to Five Major First-Year Goals
A startup can have dozens of tasks but should not have dozens of top priorities. Choose three to five outcomes covering the parts of the business that determine whether it becomes sustainable.
1. Customer Validation
Your first goal should establish whether people genuinely want what you sell.
Instead of targeting “more customers,” consider:
“Acquire 30 paying customers by June and achieve at least 10 repeat purchases by September.”
This separates interest from actual demand. Social followers and website visits may be useful leading indicators, but paying and returning customers provide stronger validation.
2. Financial Stability
Revenue alone can disguise a weak business.
Track gross margin, fixed expenses, cash balance, accounts receivable, and monthly net cash flow. A company generating $20,000 in monthly sales can still be financially unstable if collecting those sales or fulfilling orders consumes too much cash.
The IRS specifically notes that accurate records help owners monitor business progress, identify what is selling, prepare financial statements, and make management decisions.
If cash management is already a concern, understanding why small businesses run out of money should come before setting ambitious expansion targets.
3. Sales and Marketing
Connect marketing activity directly to customer acquisition.
For example:
“Generate 20 qualified leads per month from local search by Q3 and convert at least 20% into consultations.”
That tells you both how many opportunities marketing should generate and how effectively sales must convert them.
Avoid trying five channels at once. A new service business may learn more by seriously testing referrals and Google search for 90 days than by spreading a small budget across search, TikTok, Instagram, email, direct mail, and paid social simultaneously.
4. Product or Service Improvement
Early customers provide information that forecasts cannot. Set a target for collecting structured feedback, resolving common complaints, improving delivery time, or testing a revised offer.
A restaurant might monitor food waste and repeat orders. A consultant might measure project turnaround and renewals. An ecommerce company might track return rates and abandoned carts.
5. Operational Repeatability
The founder should not remain the operating system forever.
Document important recurring tasks such as invoicing, onboarding, customer support, inventory ordering, quality checks, and monthly bookkeeping.
Penn State Extension recommends goals and objectives that can be evaluated over time, with measurable objectives and deadlines that provide feedback about whether decisions are producing the intended result.
Turn Ambitions Into SMART Goals
The SMART framework remains useful because it forces vague intentions to become commitments.
SCORE defines SMART goals around being specific, measurable, achievable, relevant, and time-bound.
Compare these two statements:
“Grow our customer base.”
“Acquire 60 paying customers by December 31 while keeping customer acquisition cost below $75.”
The second goal identifies the outcome, metric, constraint, and deadline. That final constraint matters. Acquiring 60 customers by spending $20,000 may technically accomplish the customer goal while damaging the business.
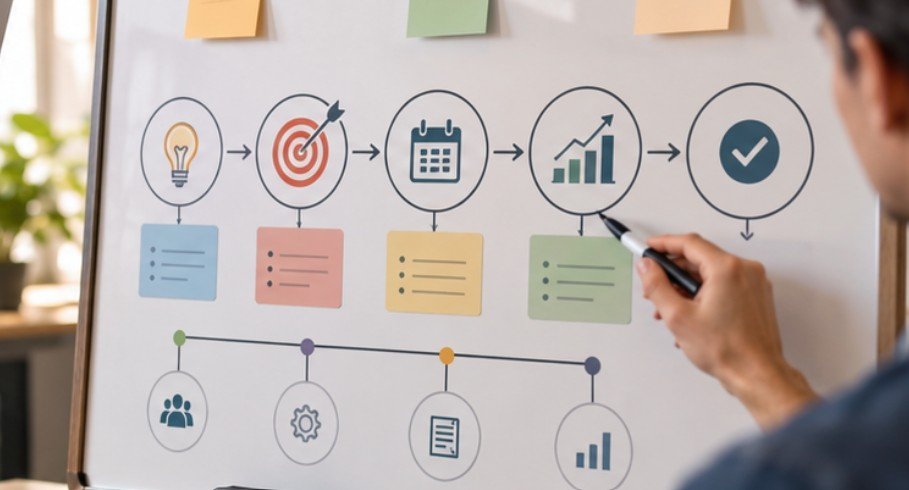
Reverse-Engineer the Year Into Four Quarters
A December goal is too distant to manage from January. The SBA recommends making first-year financial projections particularly detailed, using quarterly or even monthly forecasts. Apply the same logic to operating goals.
| Period | Main Question | Example Milestone |
| Q1 | Does the market respond? | First 10 paying customers |
| Q2 | Can sales become repeatable? | 25 total customers and reliable lead source |
| Q3 | Can the model improve? | Higher margin and repeat-purchase rate |
| Q4 | Is the business sustainable? | Positive cash flow and clear year-two plan |
Then convert quarterly milestones into monthly numbers and weekly actions. If the annual goal requires 120 customers, dividing by 12 gives a rough average of 10 per month. But early months may be slower, so a more realistic progression might be five customers monthly in Q1, eight in Q2, 12 in Q3, and 15 in Q4. That is far more useful than staring at “120 customers” all year.
Review Leading and Lagging Indicators
Revenue is a lagging indicator: it tells you what already happened. Leading indicators warn you earlier.
A landscaping company might track estimate requests. A consulting firm could track discovery calls. An online retailer could monitor product-page conversion. A subscription company might watch trial activation.
Review these weekly.
Review revenue, profit, cash flow, churn, customer acquisition cost, and larger strategic goals monthly or quarterly.
This prevents founders from waiting until December to discover that an annual target became unrealistic in April.
Build a Buffer Instead of Pretending Nothing Will Go Wrong
Goals are forecasts, not promises about the future. Equipment breaks. Suppliers increase prices. Customers pay late. Permits take longer than expected. Marketing campaigns disappoint. Build enough flexibility into both financial and operating goals to absorb those surprises.
Taxes deserve particular attention. The IRS explains that people operating businesses for themselves generally may need to make estimated tax payments during the year rather than waiting until tax filing season.
That expense belongs in cash planning from the beginning.
Do not interpret adjusting a goal as failure.
New business owners can protect their first-year plans by anticipating potential setbacks rather than assuming everything will proceed as expected.
Reviewing the common mistakes new business owners make in the first year can help entrepreneurs recognize avoidable financial missteps, unrealistic growth expectations, and operational challenges before they undermine progress.
If real customer data invalidates the original assumption, changing the target is good management.
Frequently Asked Questions
1. How many goals should a new business have in its first year?
Three to five major goals are usually enough. Concentrate on customer validation, finances, sales, operations, and product improvement rather than giving every business activity equal priority.
2. What is the most important first-year business goal?
For most startups, proving sustainable demand is more important than maximizing growth. Confirm that customers will pay, margins are workable, and enough cash remains to continue operating.
3. How often should first-year business goals be reviewed?
Review operational metrics weekly, financial performance monthly, and major strategic goals quarterly. Adjust targets when customer behavior, costs, capacity, or market conditions materially change.
4. Why is how to set business goals for the first year different from goal setting for an established company?
A new company has less historical data. Its goals must therefore test assumptions about demand, pricing, acquisition, delivery, and cash flow while established firms can rely more heavily on past performance.
Make Year One a Year of Proof
The first year does not need to produce a giant company. It needs to produce evidence.
By month 12, you should know who buys, why they buy, what acquiring them costs, whether your margins work, which marketing channels deserve investment, and how much cash the business requires. Those answers are more valuable than an impressive but arbitrary revenue target.
Set a few measurable goals, break them into quarterly milestones, review the numbers consistently, and change course when the evidence demands it. The strongest first-year plan is not the one that predicts everything correctly. It is the one that helps you notice quickly when reality differs from the forecast.