A product can sell well and still lose money. That sounds contradictory, but it happens when a business owner prices an item from material cost alone, copies a competitor, or confuses markup with profit margin. The University of Maine Extension shows why the distinction matters: an item bought for $1 and sold for $1.50 has a 50% markup on cost but only a 33.3% margin on its selling price.
Learning how to price a product for a small business therefore starts with something less glamorous than branding or competitor research: finding the true cost of making a sale.mThe strongest price sits at the intersection of three numbers—your cost floor, the customer’s willingness to pay, and the prices competing products establish in the market.
Find Your Real Cost Before Choosing a Price
The first calculation should answer a simple question: How much does one sale actually cost your business?
Start with direct product costs, often called cost of goods sold, or COGS. Depending on the business, these may include raw materials, purchased inventory, production labor, packaging that forms part of the product, and freight required to bring materials or merchandise to you.
The IRS Tax Guide for Small Business explains that COGS calculations for businesses selling merchandise can include purchases, labor, materials, supplies and certain production-related costs. Freight-in on merchandise and production materials may also form part of product cost.
Suppose you sell handmade desk organizers:
Materials: $8
Packaging: $2
Production labor: $7
Inbound freight allocation: $1
Your direct unit cost is $18.
But $18 is not necessarily your break-even selling price.
Give Every Product a Share of Your Overhead
Your business also pays expenses that cannot easily be traced to a single item: website hosting, software, insurance, rent, advertising, bookkeeping and utilities, for example.
Ignoring these costs is one reason a product can appear profitable while the overall business remains short of cash.
A practical approach is to allocate an appropriate portion of recurring overhead across expected sales.
Imagine monthly overhead is $3,000 and you reasonably expect to sell 600 products. That represents approximately $5 of overhead per unit.
Your $18 product now has an economic cost closer to $23 before payment-processing fees or other selling expenses.
Before setting your prices, make sure you have a clear picture of your business’s operating expenses. Completing your how to calculate startup costs for a small business analysis first will help you establish a more realistic pricing strategy rather than relying on incomplete financial estimates.
Margin and Markup: Know Which Number You Mean
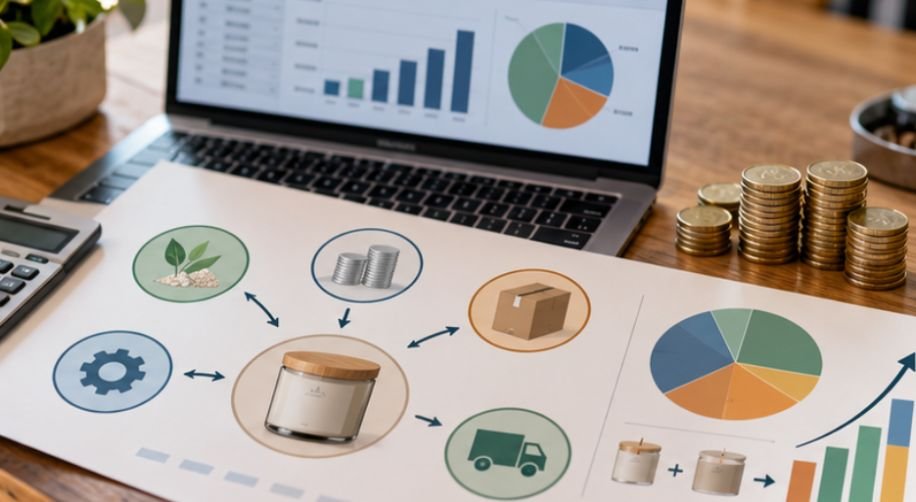
This distinction deserves special attention.
Markup compares profit with cost:
Markup = (Selling Price − Cost) ÷ Cost
Margin compares gross profit with selling price:
Margin = (Selling Price − Cost) ÷ Selling Price
Here is what that difference looks like:
| Unit Cost | Selling Price | Markup | Gross Margin |
| $20 | $30 | 50% | 33.3% |
| $20 | $40 | 100% | 50% |
| $20 | $50 | 150% | 60% |
For owners trying to reach a specific gross-margin percentage, a useful formula is:
Selling Price = Unit Cost ÷ (1 − Target Margin)
Mississippi State University Extension uses the same basic margin approach in its product-pricing guidance.
If your complete unit cost is $23 and you want a 40% gross margin:
$23 ÷ (1 − 0.40) = $38.33
That gives you a starting price—not necessarily the final one.
For more examples of pricing and break-even calculations, see Mississippi State University Extension’s product pricing guidance.
Fees Can Change the Formula
Online sellers need another layer of protection.
Suppose a marketplace or payment provider takes a percentage of every sale. Simply adding that percentage to your existing cost can understate the effect because the fee itself rises as the price rises.
For a simplified calculation:
Price = Unit Cost ÷ (1 − Target Margin − Percentage Selling Fee)
Using the $23 unit cost, a 40% target margin and a hypothetical 3% transaction fee:
$23 ÷ (1 − .40 − .03) = approximately $40.35.
Real fee structures may also contain fixed transaction charges, listing fees, fulfillment costs, returns or advertising expenses, so use the actual terms of your sales channel.
Then Ask What the Market Will Accept
Costs establish the price you need. Customers establish the price you can realistically charge.
Penn State Extension recommends considering production costs, financial goals, consumer demographics and market research before assigning product prices. Small firms may also compete against large retailers with substantial economies of scale.
Use Penn State Extension’s product-pricing resource as a starting point for evaluating those factors.
Review at least several genuinely comparable products. Compare size, durability, ingredients or materials, guarantees, shipping, presentation, brand reputation and target customer—not merely sticker price.
A $45 handcrafted product is not necessarily overpriced because a mass-market version costs $22. The real question is whether buyers understand and value the differences.
Pick a Pricing Strategy That Fits the Product
Cost-based pricing is useful for establishing your financial floor, but it should not automatically determine your final price.
Cost-plus pricing
Choosing the right pricing strategy also depends on how your business is structured and the legal responsibilities you assume as an owner.
Before settling on a long-term approach, understand the differences between an LLC vs sole proprietorship for new business, as each structure can influence liability, administrative obligations, and how you manage your business finances.
Market-based pricing
Here, competing products create a reference range. You can position your item below, near or above that range depending on your strategy.
Competing primarily on low price can be difficult for small businesses because larger companies often have purchasing and production advantages.
Value-based pricing
Value-based pricing starts with what the product is worth to a particular customer.
A specialty organizer that saves a professional an hour every week, for example, may support a higher price than its materials suggest.
SCORE cautions against treating a fixed markup as the whole pricing strategy because that can overlook what customers are willing to pay and the value they receive.
For a nonprofit small-business perspective, see SCORE’s strategic pricing guidance.
Test Your Price Before Treating It as Permanent
Pricing should behave more like an experiment than a tattoo.
Before committing to a price, run four tests.
First, calculate your break-even volume. How many units must you sell before your contribution from product sales covers fixed expenses?
Second, test a discount. If you run a 20% promotion, does the order still produce an acceptable return?
Third, test a wholesale scenario. If a retailer needs enough room to apply its own margin, can your economics support a lower wholesale price?
Fourth, ask whether your price still works if materials, freight or advertising costs increase.
The University of Maryland Extension notes that businesses should understand both fixed and variable costs and use market research to estimate the upper limit customers are willing to pay. You can review its pricing and value-added product guidance here.
Don’t Copy Competitors Blindly
Competitor prices are evidence, not instructions.
You usually do not know another company’s supplier terms, labor costs, debt, return rate, advertising expense or profitability. A competitor selling at $29.99 might have dramatically lower costs—or might simply be underpricing its own product.
Instead, use competitors to establish a market range and customer expectations. Then return to your own numbers.
Your pricing assumptions should also fit the broader goals of the company. A simple one-page business plan can help connect pricing with your revenue targets, target customer and positioning.
Frequently Asked Questions
1. What is the easiest way to price a new product?
Calculate your full unit cost, choose a target margin, compare the result with competing products, and test whether your target customers accept the price.
2. What is a reasonable profit margin for a small business product?
There is no universal percentage. Appropriate margins vary by industry, sales channel, product type, overhead, competition and customer expectations.
3. Should small businesses charge less than large competitors?
Not necessarily. Small businesses may justify higher prices through specialization, better materials, personal service, limited production, customization or stronger customer experience.
4. How often should product prices be reviewed?
Review prices whenever material, labor, shipping, marketplace or advertising costs change significantly, and conduct a broader pricing review several times a year.
Price for the Business You Need to Build
The dangerous price is not always the one customers reject. Sometimes it is the one customers eagerly accept while your margin quietly disappears.
Once you know your direct costs, allocate overhead, distinguish margin from markup and understand the market, pricing becomes a decision rather than a guess. Keep testing after launch. Watch unit economics, discounts, return rates and customer response, then adjust as the evidence changes.
The goal is not to find the lowest price that generates orders. It is to find a price customers can justify and your business can afford to keep selling.